

The global energy transition is advancing, but its direction is increasingly shaped by energy security, industrial competitiveness and the economics of available technologies. For shipping, the consequences extend beyond the choice of future fuels: changing energy consumption will also reshape cargo demand, fleet investment and the commercial outlook for different vessel segments.
That is the picture emerging from DNV’s Energy Transition Outlook 2026, the tenth edition of its annual assessment. Looking ahead to 2060, the report describes a world moving towards greater electrification and renewable energy, while remaining far from the emissions trajectory needed to meet international climate ambitions.
DNV presents its findings as a forecast of the most likely future, rather than a pathway designed to achieve climate targets. The distinction matters. Despite substantial technological progress, the organisation still expects fossil and non-fossil sources to account for roughly equal shares of primary energy in 2050.
Energy security redraws the map
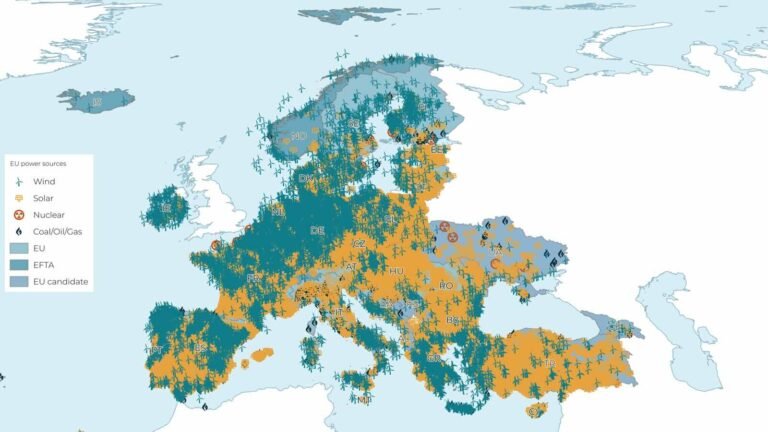
The transition is becoming increasingly uneven between countries that import fossil fuels and those that export them. Importers have stronger incentives to expand domestic renewable generation, improve efficiency and reduce their exposure to international fuel markets. Exporters, meanwhile, continue to support hydrocarbon production and the industries surrounding it.
According to DNV, the non-fossil share of primary energy increased by 2.2 percentage points across China, India and Europe over the past five years. The corresponding increase across the Middle East, North America and Russia was just 0.7 percentage points.
Investment nevertheless continues to grow. The report puts annual global expenditure on renewables at USD 1.77 trillion in 2026, compared with USD 860 billion in 2021. Yet spending alone cannot resolve the infrastructure constraints that increasingly determine how much value new generating capacity can deliver.
Electrification moves faster, networks struggle to follow
Electricity currently supplies around 21% of global final energy demand, up from 16% in 2005. DNV forecasts that its share will reach 33% in 2045, meaning electrification will advance more than twice as fast over the next two decades as it did over the previous two.
The next challenge is therefore broader than installing wind turbines and solar panels. Transmission networks, storage, flexible demand and electricity-market design must develop together to maintain reliable and affordable supply.
Artificial intelligence and data centres are attracting considerable attention, but they are only part of the demand story. DNV attributes 22% of the growth in electricity demand between today and 2040 to space cooling, 21% to electric-vehicle charging and 18% to data centres, including AI.
Battery deployment offers encouraging evidence of rapid progress: installed capacity has increased fourteenfold over five years. Transmission expansion and demand flexibility, however, are not keeping pace.
Shipping growth becomes more selective
For maritime transport, one of the report’s most consequential findings concerns the relationship between economic growth and seaborne trade. DNV expects global shipping work to plateau at approximately 77 trillion tonne-miles during the 2030s, even as the world economy continues expanding.
This does not imply a uniform decline across shipping. Instead, the cargo mix changes. Transport of fossil-energy commodities, currently accounting for about one-third of total tonne-miles, starts falling in the mid-2030s. Coal shipping declines before the end of this decade, while oil-carrier transport begins decreasing from 2030.
Liquefied-gas shipping follows a different trajectory, continuing to grow towards mid-century. Other commodities also expand, broadly offsetting the reduction in fossil-fuel cargoes. Containerisation further changes the distribution of transport demand between vessel types.
For owners, the implication is that aggregate economic growth becomes a less straightforward guide to future fleet requirements. Exposure to particular commodities and trade patterns gains greater importance.
Efficiency delivers while fuel uncertainty persists
DNV forecasts that shipping’s energy demand will peak at 13.7 exajoules annually in the early 2030s, then decline by about 20% over the following three decades. Both stabilising transport demand and efficiency improvements contribute to that reduction.
The report identifies energy efficiency as shipping’s primary decarbonisation lever. Energy consumption per tonne-mile has already fallen by an estimated 15–25% compared with business-as-usual operations over the past twenty years. Further savings of 20–30% are considered likely by 2050.
Operational measures, hull maintenance and technical improvements can therefore deliver commercial benefits while reducing fuel consumption.
The outlook for low-carbon fuels is less certain. DNV estimates that regulatory uncertainty delays maritime decarbonisation by two to three years. It has also lowered its expectations for hydrogen and its derivatives, including methanol and ammonia. Biofuels offer opportunities for existing vessels, although biomass availability limits their potential.
Progress remains insufficient
Across the global economy, DNV projects energy- and process-related CO₂ emissions falling by 44% by 2050, from around 39 billion tonnes today to 22 billion tonnes. Even that reduction leaves the world short of halfway to net zero.
The forecast points to approximately 2.3°C of warming by 2100. For shipping, the resulting message is practical: improve efficiency now, preserve investment flexibility and assess future cargo demand alongside fuel choices. The transition is changing both how ships operate and what they will be needed to carry.